Economic Outlook
India’s Economic Strength: Setting the Stage for the Next Market Rally
The Indian economy continues to demonstrate resilience despite an increasingly challenging global environment. Strong domestic consumption, infrastructure development, manufacturing expansion, services growth and sustained government capital expenditure remain the key pillars supporting India’s economic growth. With India continuing to rank among the fastest-growing major economies, its long-term structural growth story remains attractive.
However, equity markets have witnessed considerable volatility over the past year, influenced by persistent foreign institutional selling, elevated crude oil prices, currency depreciation, geopolitical tensions and global trade uncertainties. The correction has been more pronounced in mid- and small-cap stocks, while selective large-cap companies have demonstrated relatively better resilience. Market performance is increasingly becoming stock-specific, with earnings visibility, balance-sheet strength and valuations driving investor preference.
From a valuation perspective, the Nifty is currently trading below its long-term historical average, offering greater comfort from a medium- to long-term investment perspective. This valuation moderation, combined with India’s strong macroeconomic fundamentals and improving earnings prospects, could make Indian equities increasingly attractive to global investors. Discussions around a possible rationalization of long-term capital gains taxation for foreign portfolio investors could also emerge as an important catalyst. If implemented, this may improve India’s investment attractiveness and encourage foreign equity inflows, similar to the encouraging participation witnessed in India’s debt market following its inclusion in global bond indices.
Looking ahead, several domestic and international factors could influence the next phase of market performance. A recovery in corporate earnings, private-sector capital expenditure, rural and urban consumption, infrastructure spending and manufacturing activity could provide sustainable support to equities. Banking and financial services may benefit from healthy credit growth, stable asset quality and improving investment demand. Defence, capital goods, power, renewable energy, electronics manufacturing, data centers and select technology businesses also offer promising long-term structural opportunities.
Globally, the direction of US interest rates, bond yields and the dollar will remain crucial in determining international capital flows. Any easing in global monetary conditions could encourage greater allocation towards emerging markets. India may benefit from global portfolio diversification, supply-chain realignment and improving relative valuations, although competition from other emerging economies will remain relevant.
We remain constructively positive on Indian equities over the next 12 months. We believe the market could gradually transition from a liquidity-driven phase towards an earnings-driven recovery. Strong domestic SIP inflows and institutional participation provide structural support, while a potential revival in FII flows could become an additional catalyst. We favour fundamentally strong large-cap companies and selectively chosen mid-cap businesses with sustainable earnings growth, healthy balance sheets and reasonable valuations. Investors should utilize market corrections to gradually build quality portfolios rather than chase short-term momentum. The long-term India growth story remains intact. Quality, patience, disciplined asset allocation and selective stock picking will be the key drivers of wealth creation in the coming year.
Diwali Picks at a Glance
| # | Stock | CMP | Target | 12M Upside |
| 1 | Bharti Airtel Ltd. | ₹ 2,047 | ₹ 2,700 | 31.9% |
| 2 | Larsen & Toubro | ₹ 3,951 | ₹ 5,400 | 36.7% |
| 3 | Mahindra & Mahindra Ltd | ₹ 2,905 | ₹ 3,600 | 23.9% |
| 4 | Bharat Electronics Ltd | ₹ 389 | ₹ 480 | 23.4% |
| 5 | DLF Ltd. | ₹ 717 | ₹ 860 | 20% |
| 6 | Netweb Technologies India Ltd | ₹ 4,135 | ₹ 5,500 | 33% |
| 7 | BEML Ltd | ₹ 2,081 | ₹ 2,800 | 34.6% |
| 8 | Apollo Micro Systems Ltd | ₹ 418 | ₹ 520 | 24.4% |
| 9 | Indraprastha Medical Corporation Ltd | ₹ 339 | ₹ 480 | 41.6% |
| 10 | ITC Hotels Ltd | ₹ 173 | ₹ 225 | 30.1% |
| 11 | State Bank of India | ₹ 970 | ₹ 1,180 | 21.6% |
| 12 | Siemens Energy India Ltd | ₹ 2,896 | ₹ 3,800 | 31.2% |
Bharti Airtel Ltd. (CMP ₹ 2,047 TARGET ₹ 2,700 BUY | 12M UPSIDE 31.9%)
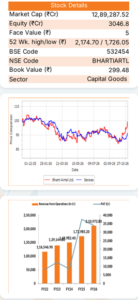
Bharti Airtel is an India’s premier and among the most trusted ICT services provider, offering a comprehensive portfolio of cutting-edge solutions for enterprises, governments, global carriers, OTT platforms and SMEs. Renowned for its innovative integrated approach, superior customer experience and unparalleled global reach, Airtel Business continues to redefine the digital landscape. With an exceptional network, it serve businesses of all sizes across India, the US, Europe, Africa, and the Middle East, Asia-Pacific and SAARC nations.
Key Takeaways
- Strong ARPU Growth & Premiumisation: India mobile ARPU increased to ₹264 in Q1FY27, supported by higher data consumption, premium customer upgrades and postpaid subscriber additions. Further tariff hikes and premiumisation offer scope for sustained ARPU improvement.
- Consistent Subscriber Growth: Added 3.3 million revenue-generating subscribers and 5 million smartphone data users in Q1FY27, reflecting strong customer traction and increasing adoption of higher-value 4G/5G services.
- Africa Business – Emerging Growth Driver: Airtel Africa offers significant growth opportunities through mobile data, 5G, broadband and Airtel Money. The proposed Airtel Money IPO could unlock additional shareholder value.
- Diversified Revenue & Digital Expansion: Growing contribution from home broadband, enterprise solutions, data centres and digital services provides additional revenue streams beyond traditional mobile connectivity, strengthening long-term earnings visibility.
- Strong Financial Performance & Operational Efficiency: Strong revenue and EBITDA growth, improving balance-sheet position and disciplined capital expenditure, coupled with energy-efficient network infrastructure, are expected to support operating margins, cash-flow generation and sustainable long-term growth.
- Strong Financial Performance: Bharti Airtel reported healthy financial growth in Q1FY27, with revenue from operations increasing 12.26% YoY to ₹58,539.10 crore, compared with ₹52,145.40 crore in Q1FY26. Profit after tax (including non-controlling interests) grew 15.73% YoY to ₹10,011.60 crore, against ₹8,650.80 crore in the corresponding quarter last year, reflecting sustained business growth and operational strength.
Outlook
Bharti Airtel is one of India’s leading and most trusted ICT service providers, with a strong presence across mobile, 5G, broadband and enterprise connectivity. Rising digital consumption, increasing data usage, expanding 5G adoption and improving average revenue per user (ARPU) are expected to support sustainable revenue growth and profitability. With its strong brand, extensive network infrastructure and established market position, the company is well-positioned to capitalise on India’s growing digital ecosystem It reported a strong financial performance in Q1FY27, with revenue from operations growing 12.26% YoY to ₹58,539.10 crore, while PAT registered a growth of 15.73% YoY to ₹10,011.60 crore, reflecting sustained business momentum and improved earnings performance. With TTM EPS of ₹46.33, the stock trades at 44.18x P/E at a CMP of ₹2,047. Considering its strong fundamentals and growth outlook, we recommend BUY, with a target price of ₹2,700, offering 31.9% upside over 12 months.
Larsen & Toubro (CMP ₹ 3,951 TARGET ₹ 5,400 BUY | 12M UPSIDE 36.7%)
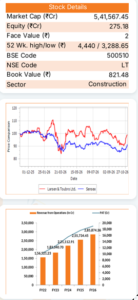
Larsen & Toubro Limited (L&T) is one a leading private sector enterprise with expertise in technology, EPC, and manufacturing. The company has earned a strong reputation for its customer-centric approach and commitment to world-class quality, which has enabled it to lead across its core business areas. With a global presence, L&T is a $32 billion multinational engaged in Engineering, Procurement, and Construction (EPC) projects, hi-tech manufacturing, and various services. The company’s relentless pursuit of excellence, innovation, and quality has been central to its continued leadership in the industry, establishing it as a trusted partner in delivering large-scale projects and solutions across diverse sectors worldwide.
Key Takeaways
- L&T achieved its highest-ever quarterly order inflows of ₹1.48 trillion in Q2Y27, registering 28% YoY growth, driven predominantly by mega energy project wins. The total group order book, including Realty, reached a record ₹8.54 trillion, providing revenue visibility over an average execution cycle of 33 months. And international order contribute 54% of the total order book.
- The six-month prospective pipeline for the core PPM business stood at ₹10.3 trillion, comprising Infrastructure at ₹5.84 trillion, Conventional Energy at ₹2.07 trillion, Green Energy at ₹2.04 trillion, and Manufacturing & Products at ₹0.33 trillion.
- L&T has reaffirmed its full-year FY27 order inflow and revenue growth guidance of 10–12%, backed by a robust 22% YoY surge in H1 order inflows. Despite ongoing global logistics disruptions, management remains confident of meeting its FY27 Precision Engineering & Manufacturing (PPM) portfolio EBITDA margin target of 7.8%. Additionally, the company upgraded its Net Working Capital (NWC) guidance, expecting year-end levels to stay comfortably well below the initial 10% target.
- The company delivered strong financial performance in Q2FY27, recording 15.84% YoY growth in revenue from operations to reach ₹78,749.94 crore up from ₹67,983.53 crore in Q2FY26. Profitability remained robust, with Profit After Tax surging 26.20% YoY to ₹5,915.15 crore, compared to ₹4,687.09 crore in the corresponding period of the previous year.
Outlook
Larsen & Toubro (L&T) is one of a leading Indian multinational engaged in engineering, EPC, technology and manufacturing, with strong exposure to India’s infrastructure development. Continued investments in roads, railways, power, defence and urban infrastructure are expected to support its long-term growth. Its diversified operations, execution capabilities and record order book of ₹8.54 trillion provide strong revenue visibility. The company delivered a robust Q2FY27 performance, with revenue from operations growing 15.84% YoY to ₹78,749.94 crore and PAT increasing 26.20% to ₹5,915.15 crore. With a TTM EPS of ₹129.85, the stock trades at 30.42x P/E at a CMP of ₹3,951. Considering its strong fundamentals and growth prospects, we recommend BUY, with a target price of ₹5,400, offering 36.7% upside over 12 months.