Economic Outlook
India’s Economic Strength: Setting the Stage for the Next Market Rally
The Indian economy continues to demonstrate resilience despite an increasingly challenging global environment. Strong domestic consumption, infrastructure development, manufacturing expansion, services growth and sustained government capital expenditure remain the key pillars supporting India’s economic growth. With India continuing to rank among the fastest-growing major economies, its long-term structural growth story remains attractive.
However, equity markets have witnessed considerable volatility over the past year, influenced by persistent foreign institutional selling, elevated crude oil prices, currency depreciation, geopolitical tensions and global trade uncertainties. The correction has been more pronounced in mid- and small-cap stocks, while selective large-cap companies have demonstrated relatively better resilience. Market performance is increasingly becoming stock-specific, with earnings visibility, balance-sheet strength and valuations driving investor preference.
From a valuation perspective, the Nifty is currently trading below its long-term historical average, offering greater comfort from a medium- to long-term investment perspective. This valuation moderation, combined with India’s strong macroeconomic fundamentals and improving earnings prospects, could make Indian equities increasingly attractive to global investors. Discussions around a possible rationalization of long-term capital gains taxation for foreign portfolio investors could also emerge as an important catalyst. If implemented, this may improve India’s investment attractiveness and encourage foreign equity inflows, similar to the encouraging participation witnessed in India’s debt market following its inclusion in global bond indices.
Looking ahead, several domestic and international factors could influence the next phase of market performance. A recovery in corporate earnings, private-sector capital expenditure, rural and urban consumption, infrastructure spending and manufacturing activity could provide sustainable support to equities. Banking and financial services may benefit from healthy credit growth, stable asset quality and improving investment demand. Defence, capital goods, power, renewable energy, electronics manufacturing, data centers and select technology businesses also offer promising long-term structural opportunities.
Globally, the direction of US interest rates, bond yields and the dollar will remain crucial in determining international capital flows. Any easing in global monetary conditions could encourage greater allocation towards emerging markets. India may benefit from global portfolio diversification, supply-chain realignment and improving relative valuations, although competition from other emerging economies will remain relevant.
We remain constructively positive on Indian equities over the next 12 months. We believe the market could gradually transition from a liquidity-driven phase towards an earnings-driven recovery. Strong domestic SIP inflows and institutional participation provide structural support, while a potential revival in FII flows could become an additional catalyst. We favour fundamentally strong large-cap companies and selectively chosen mid-cap businesses with sustainable earnings growth, healthy balance sheets and reasonable valuations. Investors should utilize market corrections to gradually build quality portfolios rather than chase short-term momentum. The long-term India growth story remains intact. Quality, patience, disciplined asset allocation and selective stock picking will be the key drivers of wealth creation in the coming year.
Diwali Picks at a Glance
| # | Stock | CMP | Target | 12M Upside |
| 1 | Bharti Airtel Ltd. | ₹ 2,047 | ₹ 2,700 | 31.9% |
| 2 | Larsen & Toubro | ₹ 3,951 | ₹ 5,400 | 36.7% |
| 3 | Mahindra & Mahindra Ltd | ₹ 2,905 | ₹ 3,600 | 23.9% |
| 4 | Bharat Electronics Ltd | ₹ 389 | ₹ 480 | 23.4% |
| 5 | DLF Ltd. | ₹ 717 | ₹ 860 | 20% |
| 6 | Netweb Technologies India Ltd | ₹ 4,135 | ₹ 5,500 | 33% |
| 7 | BEML Ltd | ₹ 2,081 | ₹ 2,800 | 34.6% |
| 8 | Apollo Micro Systems Ltd | ₹ 418 | ₹ 520 | 24.4% |
| 9 | Indraprastha Medical Corporation Ltd | ₹ 339 | ₹ 480 | 41.6% |
| 10 | ITC Hotels Ltd | ₹ 173 | ₹ 225 | 30.1% |
| 11 | State Bank of India | ₹ 970 | ₹ 1,180 | 21.6% |
| 12 | Siemens Energy India Ltd | ₹ 2,896 | ₹ 3,800 | 31.2% |
Bharti Airtel Ltd. (CMP ₹ 2,047 TARGET ₹ 2,700 BUY | 12M UPSIDE 31.9%)
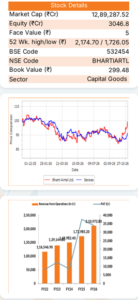
Bharti Airtel is an India’s premier and among the most trusted ICT services provider, offering a comprehensive portfolio of cutting-edge solutions for enterprises, governments, global carriers, OTT platforms and SMEs. Renowned for its innovative integrated approach, superior customer experience and unparalleled global reach, Airtel Business continues to redefine the digital landscape. With an exceptional network, it serve businesses of all sizes across India, the US, Europe, Africa, and the Middle East, Asia-Pacific and SAARC nations.
Key Takeaways
- Strong ARPU Growth & Premiumisation: India mobile ARPU increased to ₹264 in Q1FY27, supported by higher data consumption, premium customer upgrades and postpaid subscriber additions. Further tariff hikes and premiumisation offer scope for sustained ARPU improvement.
- Consistent Subscriber Growth: Added 3.3 million revenue-generating subscribers and 5 million smartphone data users in Q1FY27, reflecting strong customer traction and increasing adoption of higher-value 4G/5G services.
- Africa Business – Emerging Growth Driver: Airtel Africa offers significant growth opportunities through mobile data, 5G, broadband and Airtel Money. The proposed Airtel Money IPO could unlock additional shareholder value.
- Diversified Revenue & Digital Expansion: Growing contribution from home broadband, enterprise solutions, data centres and digital services provides additional revenue streams beyond traditional mobile connectivity, strengthening long-term earnings visibility.
- Strong Financial Performance & Operational Efficiency: Strong revenue and EBITDA growth, improving balance-sheet position and disciplined capital expenditure, coupled with energy-efficient network infrastructure, are expected to support operating margins, cash-flow generation and sustainable long-term growth.
- Strong Financial Performance: Bharti Airtel reported healthy financial growth in Q1FY27, with revenue from operations increasing 12.26% YoY to ₹58,539.10 crore, compared with ₹52,145.40 crore in Q1FY26. Profit after tax (including non-controlling interests) grew 15.73% YoY to ₹10,011.60 crore, against ₹8,650.80 crore in the corresponding quarter last year, reflecting sustained business growth and operational strength.
Outlook
Bharti Airtel is one of India’s leading and most trusted ICT service providers, with a strong presence across mobile, 5G, broadband and enterprise connectivity. Rising digital consumption, increasing data usage, expanding 5G adoption and improving average revenue per user (ARPU) are expected to support sustainable revenue growth and profitability. With its strong brand, extensive network infrastructure and established market position, the company is well-positioned to capitalise on India’s growing digital ecosystem It reported a strong financial performance in Q1FY27, with revenue from operations growing 12.26% YoY to ₹58,539.10 crore, while PAT registered a growth of 15.73% YoY to ₹10,011.60 crore, reflecting sustained business momentum and improved earnings performance. With TTM EPS of ₹46.33, the stock trades at 44.18x P/E at a CMP of ₹2,047. Considering its strong fundamentals and growth outlook, we recommend BUY, with a target price of ₹2,700, offering 31.9% upside over 12 months.
Larsen & Toubro (CMP ₹ 3,951 TARGET ₹ 5,400 BUY | 12M UPSIDE 36.7%)
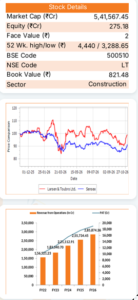
Larsen & Toubro Limited (L&T) is one a leading private sector enterprise with expertise in technology, EPC, and manufacturing. The company has earned a strong reputation for its customer-centric approach and commitment to world-class quality, which has enabled it to lead across its core business areas. With a global presence, L&T is a $32 billion multinational engaged in Engineering, Procurement, and Construction (EPC) projects, hi-tech manufacturing, and various services. The company’s relentless pursuit of excellence, innovation, and quality has been central to its continued leadership in the industry, establishing it as a trusted partner in delivering large-scale projects and solutions across diverse sectors worldwide.
Key Takeaways
- L&T achieved its highest-ever quarterly order inflows of ₹1.48 trillion in Q2Y27, registering 28% YoY growth, driven predominantly by mega energy project wins. The total group order book, including Realty, reached a record ₹8.54 trillion, providing revenue visibility over an average execution cycle of 33 months. And international order contribute 54% of the total order book.
- The six-month prospective pipeline for the core PPM business stood at ₹10.3 trillion, comprising Infrastructure at ₹5.84 trillion, Conventional Energy at ₹2.07 trillion, Green Energy at ₹2.04 trillion, and Manufacturing & Products at ₹0.33 trillion.
- L&T has reaffirmed its full-year FY27 order inflow and revenue growth guidance of 10–12%, backed by a robust 22% YoY surge in H1 order inflows. Despite ongoing global logistics disruptions, management remains confident of meeting its FY27 Precision Engineering & Manufacturing (PPM) portfolio EBITDA margin target of 7.8%. Additionally, the company upgraded its Net Working Capital (NWC) guidance, expecting year-end levels to stay comfortably well below the initial 10% target.
- The company delivered strong financial performance in Q2FY27, recording 15.84% YoY growth in revenue from operations to reach ₹78,749.94 crore up from ₹67,983.53 crore in Q2FY26. Profitability remained robust, with Profit After Tax surging 26.20% YoY to ₹5,915.15 crore, compared to ₹4,687.09 crore in the corresponding period of the previous year.
Outlook
Larsen & Toubro (L&T) is one of a leading Indian multinational engaged in engineering, EPC, technology and manufacturing, with strong exposure to India’s infrastructure development. Continued investments in roads, railways, power, defence and urban infrastructure are expected to support its long-term growth. Its diversified operations, execution capabilities and record order book of ₹8.54 trillion provide strong revenue visibility. The company delivered a robust Q2FY27 performance, with revenue from operations growing 15.84% YoY to ₹78,749.94 crore and PAT increasing 26.20% to ₹5,915.15 crore. With a TTM EPS of ₹129.85, the stock trades at 30.42x P/E at a CMP of ₹3,951. Considering its strong fundamentals and growth prospects, we recommend BUY, with a target price of ₹5,400, offering 36.7% upside over 12 months.
Mahindra & Mahindra Ltd (CMP ₹ 2,905 TARGET ₹ 3,600 BUY | 12M UPSIDE 23.9%)
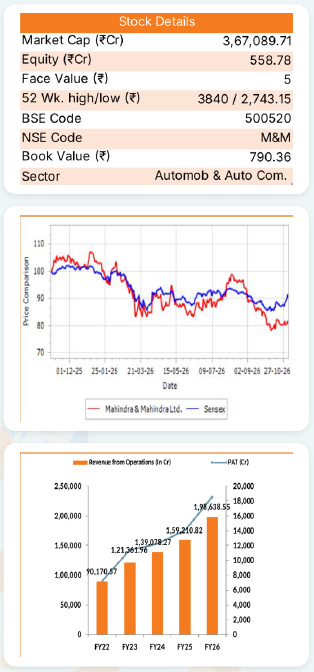
Mahindra & Mahindra Limited (M&M), the flagship enterprise of the Mahindra Group, is one of a leading Indian multinational conglomerate and one of the world’s largest tractor companies by volume. Holding market leadership across farm equipment, utility vehicles, information technology, and financial services in India, M&M manufactures a diverse portfolio of SUVs, multi-utility vehicles, pickups, commercial vehicles, and tractors across state-of-the-art facilities in Kandivali, Nashik, Igatpuri, Nagpur, Chakan, Zaheerabad, Jaipur, Rudrapur, Haridwar, Mohali, and Pithampur. It operates across 100+ countries with strong stakes in renewable energy, logistics, hospitality, and real estate.
Key Takeaways
- Strong SUV Market Position & Volume Growth: M&M continues to strengthen its leadership in the domestic SUV market, with a 25% SUV revenue market share in Q1FY27. YTD domestic utility vehicle sales grew 17% to 4,31,480 units during April–October FY27. October witnessed record monthly domestic SUV sales of 73,338 units, registering 2% YoY growth.
- Capacity Expansion & EV Opportunity: The company is aggressively expanding its automotive and electric vehicle manufacturing capabilities to cater to rising demand. Its planned expansion of EV capacity to 12,000 units per month by FY28 and overall automotive capacity to 82,000 units per month should support future volume growth. The longer-term Nagpur expansion provides additional growth potential.
- Strong Financial Performance: M&M reported 28% YoY growth in consolidated revenue to ₹58,188 crore in Q1FY27, while consolidated PAT increased 34% to ₹5,455 crore. Strong performance across automotive, farm equipment and services businesses reflects healthy earnings momentum
- Diversified Growth Opportunities: Beyond automobiles, M&M has promising growth opportunities across aerospace, defence, financial services, logistics and real estate. Its ambition to scale the aerospace business and Mahindra Lifespaces’ target of ₹10,000 crore in annual pre-sales by FY30 provide additional long-term growth drivers.
- The company delivered robust Q1FY27 financial results, posting a 27.80% YoY increase in revenue from operations to reach ₹58,187.57 crore up from ₹45,529.19 crore in Q1FY26. Profitability remained strong, with Profit after Tax growing 37.04% YoY to ₹5,997.56 crore, compared to ₹4,376.58 crore in the corresponding period of the previous year.
Outlook
Mahindra & Mahindra (M&M), the flagship company of the Mahindra Group, is one of India’s leading automotive and farm equipment manufacturers, with a strong position in the SUV and tractor segments. Its diversified business provides exposure to both urban consumption and rural economic growth. Popular SUV brands such as Scorpio, Thar and XUV, along with new product launches and its growing focus on electric vehicles, strengthen its long-term growth prospects. It continues to witness healthy demand, with domestic utility vehicle sales growing 17% YTD to 4,31,480 units and October 2026 passenger vehicle sales reaching 73,338 units. M&M also delivered robust Q1FY27 results, with revenue growing 27.80% YoY to ₹58,187.57 crore and PAT increasing 37.04% to ₹5,997.56 crore. Its TTM EPS stands at ₹148.53, while the stock trades at a P/E multiple of 19.56x at the CMP of ₹2,905. Considering its strong market position, healthy earnings growth and favourable industry outlook, we recommend BUY, with a target price of ₹3,600, indicating an upside potential of 23.9% over the next 12 months.
Bharat Electronics Ltd (CMP ₹ 389 TARGET ₹ 480 BUY | 12M UPSIDE 23.4%)
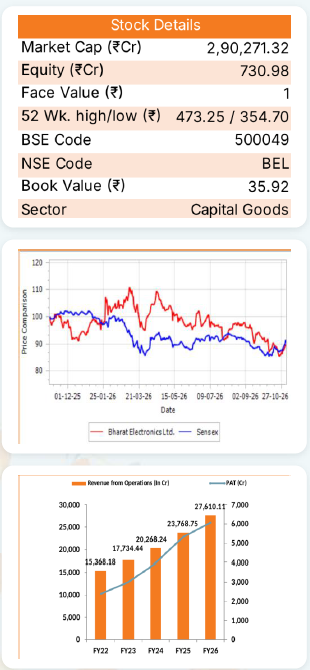
Bharat Electronics Limited (BEL) is one of the prominent public sector enterprise operating under the Department of Defence Production, Ministry of Defence. The company manufactures and supplies a wide range of electronic equipment and systems for both the defence sector and non-defence markets. BEL is a significant player in the Indian defence industry and is expanding its presence in civilian and export markets.
Key Takeaways
- Strong Order Book & Revenue Visibility: BEL has an executable order book of over ₹68,000 crore across 300+ active projects, providing strong revenue visibility for the next 2–3 years. Its diversified presence across radar systems, missile electronics, naval systems, communication and electronic warfare supports sustained business growth.
- Robust Order Inflow Pipeline: Management has guided for FY27 order inflows of ₹25,000 crore, which could exceed ₹55,000 crore, including the anticipated QRSAM project. Additionally, the Next Generation Corvette (NGC) programme offers an estimated ₹20,000 crore opportunity over the next 3–4 years, providing significant scope for order book expansion.
- Healthy Growth & Margin Outlook: Management has maintained FY27 revenue growth guidance of 15–20% and an EBITDA margin target of ~ 28%. Strong execution, operating leverage and increasing indigenisation are expected to support sustainable profitability.
- Increasing Focus on R&D & Advanced Defence Technologies: BEL plans to invest over ₹2,200 crore in R&D and approximately ₹1,200 crore in capital expenditure. Its growing focus on drone and counter-drone systems, missile electronics, electronic warfare and advanced weapon systems provides additional long-term growth opportunities
- Beneficiary of India’s Defence Indigenisation Push: Rising Govt focus on domestic defence manufacturing, import substitution and modernisation of the armed forces creates a favourable business environment. It’s established relationships with the armed forces and technological capabilities position it well to secure large defence contracts
- Strong Long-Term Growth Visibility: A combination of a large executable order book, a healthy project pipeline, increasing defence spending and expansion into next-generation technologies provides multiple growth drivers. Successful conversion of the order pipeline, coupled with consistent execution and margin stability, could support sustained earnings growth over the medium to long term
Outlook
BEL is one of a leading defence PSU under the Ministry of Defence, has established strong capabilities in radar, communication, electronic warfare and surveillance systems. Rising defence modernisation and the government’s focus on indigenous manufacturing are expected to support its long-term growth. Its executable order book of over ₹68,000 crore across 300+ projects provides strong revenue visibility, while FY27 order inflow guidance of ₹25,000 crore, with potential to exceed ₹55,000 crore, reflects a healthy pipeline. BEL delivered a strong Q2FY27 performance, with revenue from operations growing 26.51% YoY to ₹7,327.72 crore and PAT increasing 19.67% to ₹1,540.37 crore. With a TTM EPS of ₹8.75, BEL trades at 44.46x P/E. Considering its strong order book, healthy earnings growth and favourable sector outlook, we recommend BUY, with a target price of ₹480, implying an upside potential of 23.4% over the next 12 months.
DLF Ltd. (CMP ₹ 717 TARGET ₹ 860 BUY | 12M UPSIDE 20%)
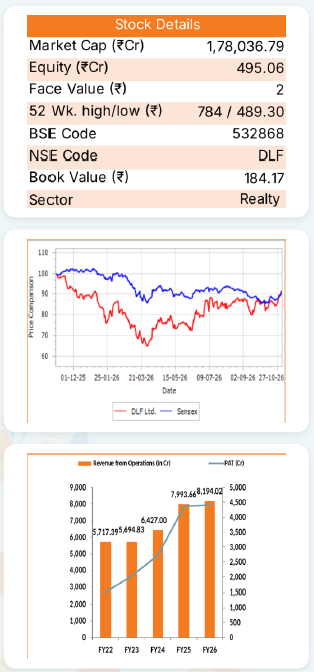
DLF is India’s one a leading real estate developer and DLF is primarily engaged in the business of development and sale of residential properties (the “Development Business”) and the development and leasing of commercial and retail properties (the “Annuity Business”). DLF has developed more than 185 real estate projects and developed an area more than 352 million square feet (approx.). DLF Group has 275 msf (approx.) of development potential across residential and commercial segment including current projects under execution and the identified pipeline.
Key Takeaways
- Strong Luxury Housing Demand & Premium Realisations: DLF recorded new sales bookings of approximately ₹3,800 crore in Q2 FY27, driven by sustained demand for its luxury residential portfolio, particularly The Dahlias and the complete sell-out of its luxury retirement project, The Aureva, generating bookings of approximately ₹1,985 crore. Its strong brand positioning and ability to command premium prices support healthy realisations and project profitability
- Strong Residential Launch Pipeline: DLF has a medium-term residential launch pipeline with estimated sales potential of approximately ₹58,230 crore. The upcoming launch roadmap includes a Mumbai project in Q3 FY27, followed by a luxury-plus development in DLF City Phase 4, Gurugram, in Q4 FY27. These launches, subject to regulatory approvals, are expected to drive fresh booking momentum and strengthen future revenue visibility.
- Management expects to sustain industry-leading occupancy rates across office and retail portfolios through high occupant retention and premier asset quality.
- A significant revenue recognition inflection point will commence in FY28, anchored by initial project completions at The Arbour and unlocking revenue from over ₹75,000 crore of cumulative launches. From FY28 onward, DLF enters a sustained three-year delivery window featuring phased project handovers across The Arbour, three phases of Privana, and Dahlias.
- Strong customer collections across launched projects are expected to generate robust operational cash flows exceeding ₹42,500 crore as construction reaches advanced stages.
Outlook
DLF is one of India’s leading real estate developers, with a strong brand, established land bank and presence across residential and commercial segments. Sustained demand for premium and luxury housing, particularly in major urban markets, is expected to support its growth. Its rental business provides recurring cash flows, while residential developments offer significant growth opportunities. The company recorded new sales bookings of ~ ₹3,800 crore in Q2FY27, reflecting healthy demand across its luxury portfolio. Revenue recognition is expected to gain momentum from FY28, driven by initial project completions at The Arbour and monetisation of its ₹75,000 crore-plus cumulative launch pipeline. At a CMP of ₹717, DLF trades at 38.86x P/E, with TTM EPS of ₹18.45. We recommend BUY, with a target price of ₹860, implying 20% upside over next 12 months.
Netweb Technologies India Ltd (CMP ₹ 4,135 TARGET ₹ 5,500 BUY | 12M UPSIDE 33%)
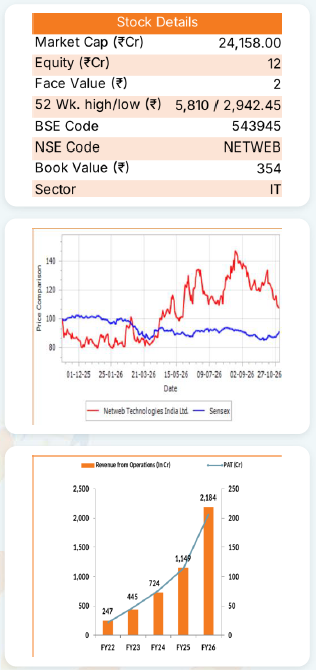
Netweb is one of India’s leading high-end computing solutions (HCS) provider, with fully integrated design and manufacturing capabilities. HCS offering comprises HPC, Private cloud and (HCI), AI systems and enterprise workstations, High performance storage (HPS) and Data Centre Servers. With more than 20 years of experience, Netweb has helped thousands of companies globally by following a customer-centric approach. Provider of servers, storage, backup, and HPC solutions that customize the right technology blocks customized to the business requirements.
Key Takeaways
- Netweb holds a confirmed order book of ₹2,629 crore (plus an L1 position of ₹653 crore, totaling ~₹3,282 crore in effective backlog) as of September 30, 2026, alongside an active business pipeline of ~₹11,152 crore.
- The Board approved establishing a 100% wholly-owned subsidiary in Taiwan to expand hardware engineering capabilities and accelerate R&D for next-generation computing architecture.
- Netweb reaffirms commitment to Make in India, maintaining complete in-house server design, schematics drafting, software integration, and domestic manufacturing operations.
- National Supercomputing Mission 2.0 represents a major growth catalyst, with Netweb targeting over 50% market share as project allocations roll out over five years.
- Netweb is actively engaging participating Cloud Service Providers to supply underlying GPU server hardware for upcoming India AI sovereign compute deployments.
- Management targets ₹4,000 crore in operational revenue for FY27 and maintains 30%–40% long-term revenue CAGR guidance, with operating EBITDA margins expected to stabilize around 13%–14%.
- Netweb Technologies delivered exceptional Q2FY27 financial results, posting revenue from operations of ₹1,323.28 crore, representing a 335.68% YoY surge from ₹303.72 crore in Q2FY26. Profitability demonstrated parallel strength, with Profit After Tax increasing 334.75% YoY to ₹136.66 crore, up from ₹31.43 crore in the corresponding prior-year period.
Outlook
Netweb Technologies is one of India’s leading high-end computing solutions providers, with strong capabilities in high-performance computing, servers and advanced computing infrastructure. Rising investments in artificial intelligence, data centres and cloud computing are expected to drive demand for its solutions, positioning the company to benefit from India’s emerging AI infrastructure ecosystem. As of September 2026, it reported a confirmed order book of ₹2,629 crore, with an additional L1 position of ₹653 crore and a business pipeline of ~ ₹11,152 crore. The company delivered a strong Q2FY27 performance, with revenue from operations growing 335.68% YoY to ₹1,323.28 crore and PAT increasing 334.45% to ₹136.66 crore. With a TTM EPS of ₹63.89, Netweb trades at 64.72x P/E at the CMP of ₹4,135. Considering its strong order book, robust earnings growth and exposure to the expanding AI infrastructure market, we recommend BUY, with a target price of ₹5,500, indicating an upside potential of 33% over the next 12 months.
BEML Ltd (CMP ₹ 2,081 TARGET ₹ 2,800 BUY | 12M UPSIDE 34.6%)
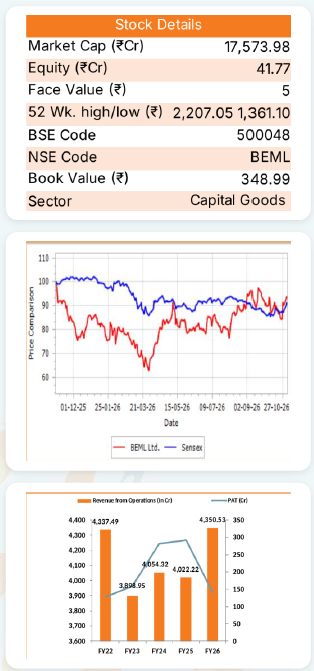
BEML Limited, a leading multi-technology ‘Schedule A’ company under the Ministry of Defence, plays a pivotal role in serving India’s core sectors, including Defence, Rail, Mining, and Construction, by offering world-class products. BEML operates in three verticals: Defence & Aerospace, Mining & Construction, and Rail & Metro. It has state-of-the-art manufacturing facilities located in Bengaluru, Kolar Gold Fields (KGP), Mysore, and Palakkad, with a strong R&D infrastructure and a nationwide sales and service network. With a legacy spanning six decades, BEML is a committed player in manufacturing earthmoving, transportation, and construction equipment, driving excellence and innovation.
Key Takeaways
- Emerging High-Speed Rail Opportunity: BEML has entered a significant new growth phase with its participation in India’s Mumbai–Ahmedabad Bullet Train project through an order worth over ₹5,400 crore for high-speed trainsets and maintenance. This provides an opportunity to build capabilities in advanced rolling stock manufacturing and participate in India’s future high-speed rail expansion.
- Strong Multi-Sector Order Pipeline: With an order book of ~ ₹16,284 crore as of June 2026, BEML has healthy business visibility across Rail & Metro, Defence and Mining & Construction. Its exposure to multiple infrastructure and industrial segments provides diversification and reduces dependence on any single business vertical.
- Rising Railway Modernisation Opportunities: Rising investments in Vande Bharat trains, metro networks, railway electrification and high-speed connectivity create a favourable demand environment. BEML’s established manufacturing capabilities and indigenous rolling stock expertise position it to compete for upcoming railway and metro projects.
- Untapped Potential in Defence & Aerospace: BEML is expanding beyond conventional military vehicles into specialised defence mobility solutions and aerospace manufacturing. Its involvement in Light Combat Helicopter fuselage manufacturing for HAL and capabilities in military transport and recovery vehicles provide opportunities to benefit from India’s defence indigenisation programme.
- Export Business Emerging as an Additional Growth Driver: It achieved record export order bookings of ~ US$107 million in FY26, reflecting growing international acceptance of its mining equipment and railway products. Expansion into overseas markets provides an additional avenue for growth beyond domestic infrastructure spending
- BEML’s long-term business structure targets a 65%–70% revenue contribution from its Rail, Metro, and Defense segments, with Mining delivering the remaining 30%–35%.
Outlook
BEML Lts is one of a leading defence PSU under the Ministry of Defence, operates across three key growth segments: defence, railways and mining & construction. Government spending on railway modernisation, metro expansion, defence manufacturing and infrastructure development is expected to support its long-term growth. The company has an executable order book exceeding ₹16,000 crore, providing strong revenue visibility, alongside a ₹35,000–40,000 crore opportunity pipeline. Management targets FY27 order inflows of ~ ₹20,000 crore, supported by a healthy project pipeline, including international metro opportunities. With a TTM EPS of ₹21.43, the stock trades at 97.11x P/E at a CMP of ₹2,081. Considering its strong order book and growth prospects, we recommend BUY, with a target price of ₹2,800, offering 34.6% upside over 12 months.
Apollo Micro Systems Ltd (CMP ₹ 418 TARGET ₹ 520 BUY | 12M UPSIDE 24.4%)
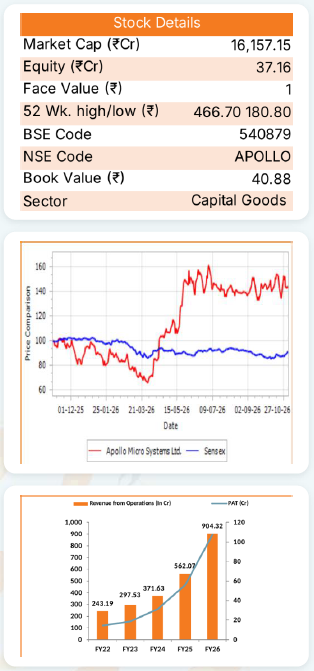
Apollo Micro Systems Limited (AMS) is one of a leading multidisciplinary Indian defense technology company, with a legacy spanning over four decades in delivering advanced security solutions. Having evolved from a component-level specialist into a full-spectrum defense solutions provider, AMS plays a pivotal role in the indigenous design, development, and production of mission-critical systems across Land, Air, Sea, and Space domains. Backed by state-of-the-art R&D, in-house manufacturing, and specialized system integration infrastructure, the company is strategically positioned as a Tier-I Defence Prime. AMS actively supports flagship strategic programs for the DRDO, DPSUs, and the Indian Armed Forces, reinforcing national security under the Atmanirbhar Bharat initiative.
Key Takeaways
- DRDO Technology Advantage: Received Transfer of Technology (ToT) for the Semi-Active Laser Homing System, strengthening its capabilities in indigenous precision-guided missile systems and advanced defence electronics.
- Strong Order Book Visibility: Reported a record consolidated order book of ₹1,765 crore as of September 2026, with management targeting ₹2,000+ crore by March 2027, excluding MIGM. The potential order book could rise to ₹4,500–5,000 crore following the anticipated MIGM order.
- Growing Defence Opportunities: Positioned across key indigenous defence programmes, including MIGM, QRSAM, Akash, Pinaka and torpedo systems. Its specialised electronic subsystems and proprietary technologies provide competitive advantages
- Strategic Acquisition & Integration: The proposed acquisition of Premier Explosives can strengthen its presence across defence electronics, explosives, propellants and warhead systems, creating an integrated defence manufacturing platform.
- Strong R&D and Expansion Plans: Investing approximately 8% of revenue in R&D, Apollo aims to transition into a global defence OEM over the next 5–6 years, moving towards higher-value indigenous defence products and integrated systems.
- Strong Growth Outlook: Management has guided for 35–45% revenue growth in FY27, supported by a growing order pipeline, capacity expansion and increasing defence indigenisation. Successful conversion of MIGM and other large opportunities could provide additional upside.
Outlook
Apollo Micro Systems (AMS) is one of a leading Indian defence technology company specialising in defence electronics and advanced security solutions. India’s increasing focus on indigenous defence manufacturing and rising defence expenditure are expected to support its long-term growth. The company reported a record consolidated order book of ₹1,765 crore as of September 2026, providing strong revenue visibility. Management targets 35–45% standalone revenue growth in FY27 and an order book exceeding ₹2,000 crore by March 2027, excluding the potential MIGM contract. AMS delivered a strong Q2FY27 performance, with revenue growing 72.31% YoY to ₹388.15 crore and PAT increasing 53.71% YoY to ₹46.15 crore. At a CMP of ₹418, the stock trades at 112.06x P/E, with TTM EPS of ₹3.73. Considering its growth prospects, we recommend BUY, with a target price of ₹520, indicating 24.4% upside over 12 months.
Indraprastha Medical Corporation Ltd (CMP ₹ 339 TARGET ₹ 480 BUY | 12M UPSIDE 41.6%)
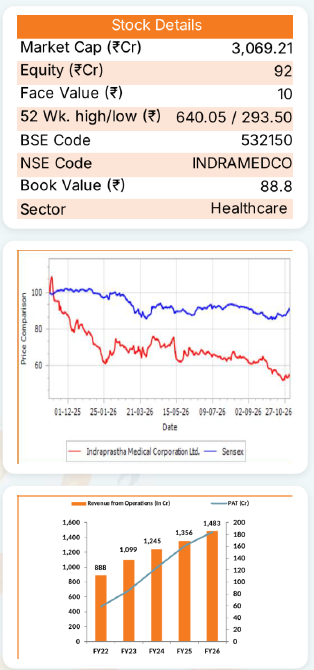
Indraprastha Medical Corporation Ltd. provides comprehensive diagnostic, medical, and surgical healthcare services across a broad range of specialties, including oncology, cardiology, neurology, orthopedics, gastroenterology, and pediatrics. Equipped with advanced diagnostic infrastructure—such as radiodiagnosis, nuclear medicine, endoscopy labs, and blood bank facilities—the hospital delivers high-precision clinical care alongside complex surgeries ranging from neuro and cardiothoracic to joint replacement and cosmetic procedures. To support emergency and continuous patient care, the company operates dedicated ambulance, air ambulance, and outpatient consultation services.
Key Takeaways
- Strong Clinical Expertise: The hospital continues to build its reputation in advanced medical treatments, performing several rare and complex procedures, including India’s first dual-chamber leadless pacemaker implantation through a prosthetic tricuspid valve. Its specialised medical teams and research capabilities provide a competitive advantage.
- Increasing Use of Advanced Technology: Adoption of AI-based clinical systems, connected patient monitoring, advanced surgical equipment and robotic rehabilitation facilities is helping improve treatment quality, patient monitoring and operational efficiency.
- Strong Brand & International Patient Base: Backed by the Apollo brand and its established presence in Delhi-NCR, the hospital attracts patients seeking specialised treatments. Its international patient services also provide opportunities to benefit from growing medical tourism in India.
- Growing Demand for Specialised Healthcare: Rising healthcare spending, increasing health insurance coverage and demand for advanced treatments in areas such as cardiology, oncology and neurology provide long-term growth opportunities for the hospital.
- Steady Financial Performance: Q2FY27 revenue increased 8.35% YoY to ₹412.85 crore, while net profit grew 8.33% to ₹53.58 crore. The company continues to deliver steady business growth supported by its established hospital operations.
- Expansion to Support Future Growth: The proposed addition of around 350 beds at its Sarita Vihar facility, involving an estimated investment of ₹800 crore excluding land, is expected to strengthen its capacity and support future revenue growth. The expansion is targeted for completion around Q4 FY28.
Outlook
Indraprastha Medical Corporation Ltd is one of a leading healthcare provider offering specialised medical, diagnostic and surgical services across multiple disciplines. Rising healthcare expenditure, increasing demand for advanced treatments and greater awareness of quality healthcare are expected to support its long-term growth. The hospital demonstrated clinical excellence through seven rare, first-in-India medical procedures, including a novel dual-chamber leadless pacemaker insertion. Its research capabilities also gained recognition with the WHO acknowledgement of a newly identified HLA allele. It delivered steady Q2FY27 results, with revenue growing 8.35% YoY to ₹412.85 crore and PAT increasing 8.33% YoY to ₹53.58 crore. With a TTM EPS of ₹20.95, the stock trades at 16.18x P/E at a CMP of ₹339. Considering its established market position, consistent financial performance and attractive valuations, we recommend BUY, with a target price of ₹480, indicating 41.6% upside over the next 12 months.
ITC Hotels Ltd (CMP ₹ 173 TARGET ₹ 225 BUY | 12M UPSIDE 30.1%)
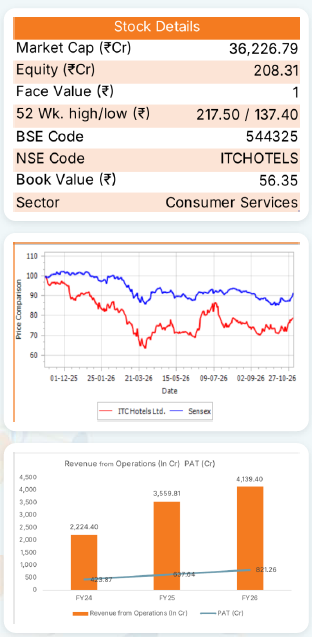
ITC Hotels has grown into one of India’s premier hospitality chains, with over 140 properties across 90+ destinations. The brand seamlessly blends India’s rich heritage with globally benchmarked service standards through six distinct brands: ITC Hotels and Mementos (luxury), Storii (premium boutique), Welcomhotel (upper upscale), Fortune (midscale), and WelcomHeritage (heritage leisure). A pioneer in sustainable hospitality, ITC Hotels’ owned properties are LEED Platinum certified, earning the 2024 USGBC Leadership Award for Organisational Excellence. The group is also renowned for its iconic culinary brands such as Bukhara, Dum Pukht, Avartana, and Ottimo. Through the ITC Hospitality Management Institute and WGSHA, ITC Hotels continues to shape future leaders in global hospitality.
Key Takeaways
- The operational footprint currently stands at 156 hotels (~14,300 keys), supported by an active managed pipeline of 84 hotels (~8,200 keys) and five owned luxury developments that will add over 700 keys between 2027 and 2030.
- The group is executing an asset-right expansion strategy to scale its total operational portfolio to 250 hotels exceeding 22,000+ keys by 2031, while expanding large banqueting projects in key markets to capture high-margin convention revenue.
- Favorable demand-supply dynamics and limited new room supply across major Indian urban markets support strong pricing power, positioning management for sustained performance through H2FY27 driven by peak winter travel, weddings, and corporate events.
- Investments in AI, data automation, and digital guest infrastructure continue to optimize property overheads and elevate user experiences, while management maintains focus on monitoring input inflation, geopolitical risks, and climate-related disruptions.
- In Q2FY27, ITC Hotels Ltd achieved a consolidated Average Room Rate of ₹12,800 (+14% YoY). Driven by a 76% occupancy rate (+481 bps), RevPAR rose 21% YoY to ₹9,700, maintaining a 44% RevPAR premium over luxury and upper-upscale industry competitors.
- ITC Hotels Limited delivered a strong financial performance in Q2FY27, with revenue from operations expanding 25.57% YoY to ₹1,054.14 crore up from ₹839.48 crore in Q2FY26, while net profit after tax surged 52.04% YoY to ₹202.65 crore up from ₹133.29 crore in Q2FY26.
Outlook
ITC Hotels is one of India’s leading hospitality chains, with a strong brand portfolio across luxury and premium segments. Rising domestic tourism, business travel and disposable incomes are expected to support the industry’s long-term growth. The company operates 156 hotels with ~ 14,300 keys, supported by a managed pipeline of 84 hotels and five owned luxury developments. Its asset-right expansion strategy aims to scale the portfolio to 250 hotels with over 22,000 keys by 2031, providing significant growth opportunities. ITC Hotels delivered a strong Q2FY27 performance, with revenue growing 25.57% YoY to ₹1,054.14 crore, while PAT surged 52.04% YoY to ₹202.65 crore. With a TTM EPS of ₹4.48, the stock trades at 38.62x P/E at a CMP of ₹173. Considering its expansion plans, strong brand positioning and healthy earnings growth, we recommend BUY, with a target price of ₹225, indicating 30.1% upside over the next 12 months.
State Bank of India (CMP ₹ 970 TARGET ₹ 1,180 BUY | 12M UPSIDE 21.6%)
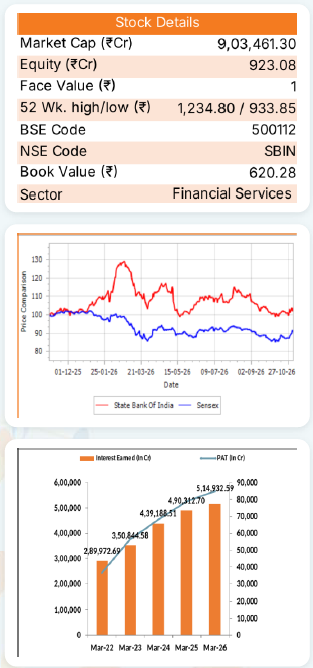
State Bank of India (SBI) is one a leading Indian public sector banking and financial services institution, with a legacy spanning over 200 years, SBI is the most trusted bank in India, serving over 500 million customers. The bank boasts an asset base of over ₹61 trillion and operates through a vast network of 23,321 branches, 63,580 ATMs, and 82,900 BC outlets. SBI’s diversified portfolio includes subsidiaries such as SBI General Insurance, SBI Life Insurance, SBI Mutual Fund, and SBI Card. With a global presence across 245 offices in 29 countries, SBI continues to innovate and deliver sustainable, customer-centric banking solutions, upholding its core values of service, transparency, ethics, and sustainability.
Key Takeaways
- State Bank of India (SBI) expanded its total business volume to ~₹115 trillion, propelled by a 12.27% YoY growth in total deposits to ₹63 trillion and a broad-based 17.84% YoY increase in total advances to ₹52 trillion across retail, corporate, and agricultural segments.
- Asset quality strengthened to multi-decade best, with the Gross NPA ratio improving by 34 bps YoY to 1.39% and the Net NPA ratio tightening to 0.36%, reflecting rigorous credit underwriting and strong recovery mechanisms.
- Management reiterated its key annual targets, reaffirming a Return on Assets (ROA) of ~1.0%, a Domestic Net Interest Margin (NIM) of ≥3.0%, and a Return on Equity (ROE) of ≥15.0% across economic cycles.
- The bank maintained its FY27 credit growth guidance of 14% to 15% YoY, driven by anticipated credit demand during the H2 festive season and expanding corporate capex requirements.
- State Bank of India successfully raised $10.9 billion under the FCNRB window—exceeding its $10 billion target to support national reserve liquidity goals with $8.83 billion safely deployed across foreign offices via existing credit lines, limiting the foreign office NIM impact to a modest 2 bps compression.
- In Q2FY27, Net Interest Income (NII) grew 14.69% YoY to ₹49,143 crore up from ₹42,847 crore in Q2FY26, while Net Profit expanded 14.28% YoY to ₹23,038 crore up from ₹20,160 crore in Q2FY26, supported by Net Interest Margin (NIM) expansion to 3.11% from 3.08%.
Outlook
State Bank of India, India’s largest public sector bank, has a strong deposit franchise, extensive distribution network and a leading position in the banking sector. Rising credit demand, supported by economic growth, is expected to drive its long-term business expansion. The bank’s total business reached ~ ₹115 trillion, with deposits growing 12.27% YoY to ₹63 trillion and advances increasing 17.84% to ₹52 trillion. Asset quality improved significantly, with Gross NPA and Net NPA declining to 1.39% and 0.36%, respectively. SBI delivered a strong Q2FY27 performance, with NII growing 14.69% YoY to ₹49,143 crore and net profit increasing 14.28% to ₹23,038 crore. NIM improved to 3.11%. With TTM EPS of ₹97.97, the stock trades at 9.9x P/E at a CMP of ₹970. Considering its healthy asset quality, strong business growth and attractive valuations, we recommend BUY, with a target price of ₹1,180, indicating 21.6% upside over 12 months.
Siemens Energy India Ltd (CMP ₹ 2,896 TARGET ₹ 3,800 BUY | 12M UPSIDE 31.2%)
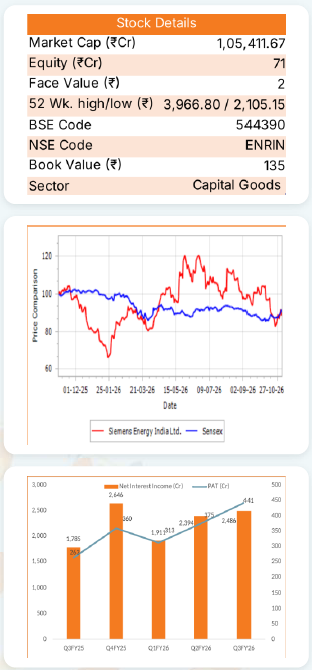
Siemens Energy India Ltd is one of a leading energy technology Provider, delivering integrated solutions across power generation and transmission systems. Siemens Energy India Limited (SEIL) works with its customers and partners on energy systems for the future, thus supporting the transition to a more sustainable world. With its portfolio of products, solutions and services, it covers almost the entire energy value chain – from power and heat generation and transmission to storage.
Key Takeaways
- Total order backlog expanded 16.4% YoY to ₹19,331 crore (₹193.31 billion), driven by a 27.6% surge in Power Transmission backlog to ₹1,349 crore, providing high revenue visibility despite a minor 3.2% decline in Power Generation backlog to ₹584 crore.
- Management is strategically positioning grid flexibilization, advanced switchgear, and power generation technology to capitalize on national grid expansion under “Viksit Bharat”, along with macro tailwinds from India adding over 30 GW of renewable capacity in H1 CY2026 and rising global AI datacenter energy demand.
- Order wins were highlighted by a major domestic order for a Large Industrial Steam Turbine from a prominent metals firm, Waste Heat Recovery solutions (3×45 MW) in Eastern India, and an international service order expanding the high-margin global service footprint.
- The company remains committed to operational climate neutrality by 2030, having already achieved a 44% reduction in Scope 1+2 emissions alongside a 30% reduction in Scope 3 upstream emissions.
- Expanded high-voltage infrastructure execution across domestic and international markets by commissioning a 220 kV GIS substation for a major data center in Maharashtra, delivering 220 kV GIS equipment for an African metro project, and supplying 240 MVA power transformers to a US energy utility.
- Siemens Energy India Ltd delivered a strong financial performance in Q3FY26, with revenue from operations increasing 39.3% YoY to ₹2,486 crore up from ₹1,785 crore in Q3FY25, while profit after tax surged 67.8% YoY to ₹441 crore up from ₹263 crore in Q3FY25.
Outlook
Siemens Energy India Ltd. is one a leading energy technology provider, offering integrated solutions across power generation and transmission. Rising electricity consumption, renewable energy expansion and increasing investments in grid modernisation are expected to drive demand for reliable power infrastructure. The company is well-positioned to benefit from these opportunities through its technology and engineering capabilities. Its total order backlog grew 16.4% YoY to ₹19,331 crore, providing strong revenue visibility. Siemens Energy India delivered a robust Q3FY26 performance, with revenue growing 39.3% YoY to ₹2,486 crore, while PAT surged 67.8% YoY to ₹441 crore. With a TTM EPS of ₹41.79, the stock trades at 69.29x P/E at a CMP of ₹2,896. Considering its strong order book, healthy earnings growth and favourable power infrastructure outlook, we recommend BUY, with a target price of ₹3,800, indicating an upside potential of 31.2% over the next 12 months.
Disclaimer:
InCred Markets Limited (“the Company”), Formerly known as Elite Wealth Limited (The company is Wholly Owned Subsidiary of InCred Capital Financial Services Limited) does/ does not do business with companies covered in its research reports. Investors should be aware that the Company may/may not have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only information in making their investment decision and must exercise their own judgment before making any investment decision.
For analyst certification and other important disclosures, see the Disclosure Appendix, or go to www.incredmarkets.com. Analysts employed by the Company are registered/qualified as research analysts with SEBI in India. (SEBI Registration No.: INH100002300)
Disclosure Appendix
Analyst Certification (For Reports)
Vindhyachal Prasad, InCred Markets Limited, vindhyachal@elitestock.com
The analyst(s) certify that all of the views expressed in this report accurately reflect my/our personal views about the subject company or companies and its or their securities. I/We also certify that no part of my compensation was, is or will be, directly or indirectly, related to the specific recommendations or views expressed in this report. Unless otherwise stated, the individuals listed on the cover page of this report are analysts in the Company.
As to each individual report referenced herein, the primary research analyst(s) named within the report individually certify, with respect to each security or issuer that the analyst covered in the report, that:
1. All of the views expressed in the report accurately reflect his or her personal views about any and all of the subject securities or issuers; and
2. No part of any of the research analyst’s compensation was, is, or will be directly or indirectly related to the specific recommendations or views expressed in the report. For individual analyst certifications, please refer to the disclosure section at the end of the attached individual notes.
Research Excerpts
This note may include excerpts from previously published research. For access to the full reports, including analyst certification and important disclosures, investment thesis, valuation methodology, and risks to rating and price targets, please visit www.incredmarkets.com.
Company-Specific Disclosures
Important disclosures, including price charts, are available and all InCred Markets Limited covered companies by visiting www.incredmarkets.com. or emailing research@elitestock.com with your request. The Company may screen companies based on Strategy, Technical, and Quantitative Research. For important disclosures for these companies, please e-mail research@elitestock.com.
Options related research:
If the information contained herein regards options related research, such information is available only to persons who have received the proper option risk disclosure documents. For a copy of the risk disclosure documents, please contact your Broker’s Representative or visit the OCC’s website at www.incredmarkets.com.
Other Disclosures
All research reports made available to clients are simultaneously available on our client websites. Not all research content is redistributed, e-mailed or made available to third-party aggregators. For all research reports available on a particular stock, please contact your respective broker’s sales person.
Ownership and material conflicts of interest Disclosure
InCred Markets Limited policy prohibits its analysts, professionals reporting to analysts from owning securities of any company in the analyst’s area of coverage. Analyst compensation: Analysts are salary based permanent employees of the Company. Analyst as officer or director: The Company’s policy prohibits its analysts, persons reporting to analysts from serving as an officer, director, board member or employee of any company in the analyst’s area of coverage.
Use of Artificial Intelligence Tools (AI)
• The Research Analyst may use Artificial Intelligence (AI) tools, to the extent applicable, for supporting research activities such as data analysis, processing of information, research assistance and preparation of research materials.
• AI tools are used only as supporting tools in the research process. All research recommendations and services remain subject to the Research Analyst’s review, verification and professional judgment. The Research Analyst remains responsible for the research services provided, including the accuracy and integrity of the information used, protection of client data, confidentiality and compliance with applicable laws and SEBI regulations.
• The extent and nature of AI usage may vary depending on the research activity. The Research Analyst shall make additional disclosures regarding AI usage whenever required.
Country Specific Disclosures
India – For private circulation only, not for sale. Legal
Entities Disclosures
InCred Markets Limited (Formerly known as Elite Wealth Limited) (IML henceforth), is a SEBI Registered Analyst having registration no. INH100002300, having its registered office at Casa Picasso, Golf Course Extension, Near Rajesh Pilot Chowk, Radha Swami, Sector-61, Gurgaon-122001 Haryana, Telephone: 0120-4477777, and Website: www.incredmarkets.com. There is no material conflict of interest with the subject company. The company and the Research Analyst have no actual or beneficial interest of one percent or more in the subject company.
The Company discloses all material information about itself including its business activity, disciplinary history, the terms and conditions on which it offers research report, details of associates and such other information as is necessary to take an investment decision, including the following:
1. Reports
a) IML or his associate or his relative has no financial interest in the subject company and the nature of such financial interest;
b) IML or its associates or relatives, have no actual/beneficial ownership of one %. or more in the securities of the subject company, at the end of the month immediately preceding the date of publication of the research report or date of the public appearance;
c) IML or its associate or his relative, has no other material conflict of interest at the time of publication of the research report or at the time of public appearance;
2. Compensation
a) IML or its associates have not received any compensation from the subject company in the past twelve months;
b) IML or its associates have not managed or co-managed public offering of securities for the subject company in the past twelve months;
c) IML or its associates have not received any compensation for investment banking or merchant banking or brokerage services from the subject company in the past twelve months;
d) IML or its associates have not received any compensation for products or services other than investment banking or merchant banking or brokerage services from the subject company in the past twelve months;
e) IML or its associates have not received any compensation or other benefits from the Subject Company or third party in connection with the research report.
3. In respect of Public Appearances
a) IML or its associates have not received any compensation from the subject company in the past twelve months;
b) The subject company is not now or never a client during twelve months preceding the date of distribution of the research report and the types of services provided by IML